
Location and Affordability
Choosing the right neighbourhood is one of the most critical decisions for first home buyers in Australia. It involves balancing affordability with long‑term value. First, you’ll want to check whether the suburb or regional town you’re considering falls within the property price caps for government schemes such as the First Home Guarantee or Help to Buy scheme—because only homes below those thresholds qualify. Price caps vary by city: for example, in late 2025, Sydney metro cap is around AUD 1.3 million, Queensland metro cap AUD 1 million, Victoria metro AUD 950K, WA AUD 850K, SA AUD 900K, Tasmania AUD 700K, and NT AUD 600K. Make sure the suburb’s typical house prices don’t exceed these thresholds.
Knowing current market values in your target area also helps you assess whether a suburb is genuinely affordable for your deposit and mortgage budget. Many first home buyers rely on the Home Guarantee Scheme (including First Home Guarantee, Regional First Home Buyer Guarantee, and Family Home Guarantee) which often only require 2–5 percent deposit with no Lenders’ Mortgage Insurance (LMI) if you meet the eligibility criteria (citizenship, income caps, owner‑occupier requirement).
Access to Grants and Shared Equity Schemes
Each Australian state and territory also offers its own First Home Owner Grant (FHOG) for new or substantially renovated homes. For example, Queensland offers up to AUD 30,000 for new builds under AUD 750K, while states like NSW and Victoria offer about AUD 10,000 under certain value limits. Be sure the suburb you’re targeting qualifies under the relevant state’s thresholds and grant conditions.
The federal Help to Buy (shared equity) scheme allows up to 40 percent equity from the government for new homes or 30 percent for established homes with just 2 percent deposit, subject to income caps that were recently increased to AUD 100K for singles and AUD 160K for couples or single parents. Many suburbs in regional areas may also be eligible for the Regional First Home Buyer Guarantee, which offers the same deposit advantages if you’ve lived in, or adjacent to, the regional area for 12 months before applying.
Community Facilities and Livability
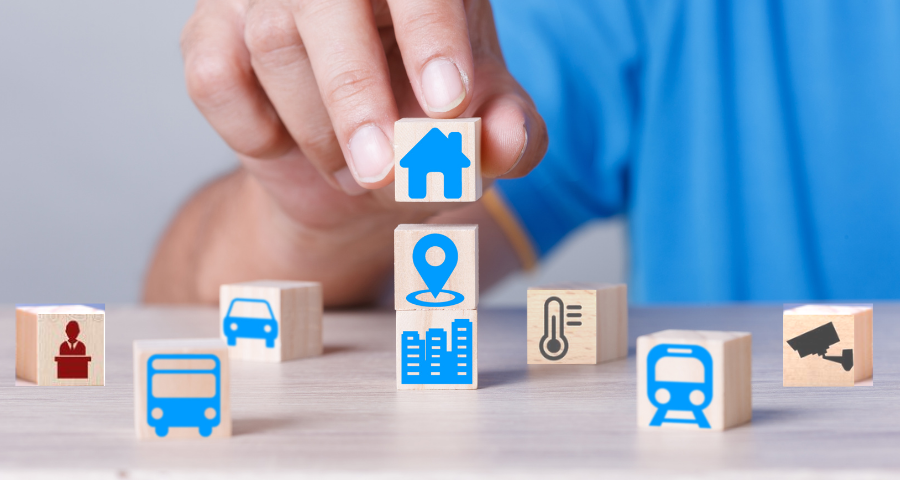
Beyond financial support, what makes a suburb a great neighbourhood for first home buyers? A combination of local amenities, schools, public transport access, green spaces, shopping and dining options, and services like healthcare should all be considered.
Look for areas with good access to reputable primary and secondary schools—both public and private—as this builds future resale value and makes life easier if you are planning a family. Quality healthcare infrastructure, such as local GP clinics, dental care and hospitals nearby, adds peace of mind.
Access to public transport is especially beneficial in bigger cities. If the suburb has bus services, train or light rail access within a short walk or drive, that improves mobility and lifestyle.
Local parks, playgrounds, walking and cycling paths help support community and physical well‑being. Suburbs with maintained green spaces, suburban reserves, or proximity to rivers or beaches can enhance long‑term appeal.
Future Growth and Infrastructure Planning
Before buying, research local council and state planning instruments. Check if any major infrastructure projects are underway—such as new rail links, road upgrades, schools, hospitals or shopping precinct developments—which can increase property value over time.
Some suburbs are part of urban infill projects or transit‑oriented development zones. These areas often gain improved connectivity and amenities, but can also experience short‑term construction and population growth. A historically stable yet improving suburb may offer lower entry prices coupled with future upside.
Demographics and Lifestyle Fit
Different suburbs cater to different lifestyles: families, professionals, retirees, first home buyers, or mixed communities. Visiting at different times of the week and day helps assess noise, traffic levels, and whether the neighbourhood aligns with your lifestyle.
Online demographic profiles give insights into average age, household size, work patterns (e.g. many young professionals vs. families), and median income. A suburb with many renters may have different dynamics than one with a majority of owner‑occupiers. High owner‑occupancy rates often signal community stability.
Safety and Local Services
Check local crime statistics and ask residents about their experiences. Lower crime rates contribute to peace of mind and help maintain property value. Suburbs with visible community policing, neighbourhood support groups, and well‑lit public spaces are preferable.
Essential services like shopping centres, childcare, post offices, libraries, gyms, and community centres matter too. A suburb where daily errands can be done within a short walk or drive increases convenience and quality of life.
Affordability vs Lifestyle Trade-offs
Often, suburbs promising lower prices might lack transport links or amenities, while those with top facilities may sit above government scheme caps. You should weigh the extra cost of slightly pricier suburbs against potential savings from longer-term resale value and livability benefits.
If you’re eligible for schemes like the Home Guarantee or FHOG, you might be able to stretch into a slightly better suburb while still keeping within deposit and value limits. For example, electrifying your commute or access to train corridors could justify a higher initial price if it avoids needing a car.
Future‑proof Features
Consider whether the neighbourhood supports long-term trends like walkability, high‑speed internet, access to EV charging or solar‑enabled homes, nearby coworking spaces, and proximity to employment hubs. A neighbourhood with climate‑resilient features—shade trees, flood management, or elevation control—might be more future‑proof.
Choosing a suburb with space for shared facilities, potential for infill investment, or access to regional town centres with growth prospects can help future value.
Navigating Scheme Eligibility in Practice
When exploring suburbs, always check the postcode-based eligibility tools for the First Home Guarantee price caps and Regional First Home Buyer Guarantee regions. You’ll also want to verify that the suburb qualifies under your state’s First Home Owner Grant rules—using official government websites to confirm caps and migration requirements.
If you’re buying in a regional area, you must have lived in that region or an adjacent one for 12 months prior to your Home Loan Date to qualify for the regional scheme.
Your lender will assess your eligibility for these schemes, but doing your homework early is essential to ensure the suburb you choose won’t disqualify you later in the process.
Tips for Suburb Research
Walk or drive through the area on weekdays and weekends. Visit local cafés, schools, shops to talk with residents. Use online tools to check median sale prices, days on market, rental yields, and demographic makeup. Look at council websites for long‑term strategy plans and zoning changes. Use government postcode tools to check price cap thresholds and scheme eligibility.
Balancing Short‑Term Entry and Long‑Term Value
It’s tempting to prioritise simply entering the market, but suburbs with strong fundamentals (good schools, transport, amenities, future infrastructure) often deliver stronger capital growth over time. Coupling that with government schemes like FHBG, FHOG or Help to Buy can reduce upfront costs without sacrificing quality location.