
Buying your first home in Australia is a major life event. With property prices fluctuating and real estate jargon flying left and right, the process can be overwhelming. One of the most crucial yet often misunderstood parts of buying a property is the valuation process. Whether you’re buying in Sydney, Melbourne, Brisbane, or a regional town, understanding how property valuations work can save you from financial missteps.
This guide breaks down exactly what property valuation means, how it affects your first home purchase, and how it connects with government support schemes like the First Home Owner Grant (FHOG) and First Home Guarantee (FHG).
What Is a Property Valuation?
A property valuation is a formal assessment of a home’s market value, conducted by a certified valuer. It’s not the same as the selling price or what a seller hopes to get. It’s an objective estimate of what the property is worth in current market conditions. The valuation considers recent sales in the area, the home’s condition, location, size, improvements, and local demand.
Valuations in Australia are often done when a buyer seeks finance, and lenders want to ensure the property is worth what the buyer is paying. It protects both the bank and the buyer from overpaying.
Why Valuation Matters for First Home Buyers in Australia
In Australia, property prices vary significantly between states and cities. First home buyers face fierce competition in some areas and may be tempted to rush or overpay. A formal valuation gives you a financial safety net.
When you apply for a home loan, the lender will require a valuation of the property you’re intending to purchase. This valuation determines how much the bank is willing to lend you. If the property is valued lower than your purchase price, the bank may reduce the loan amount, and you’ll have to make up the shortfall yourself.
Valuation can also influence eligibility for government schemes like:
First Home Owner Grant (FHOG) – Most states offer a grant to eligible first home buyers, typically for new homes. Property value caps apply, and valuations may be used to confirm eligibility.
First Home Guarantee (FHG) – Part of the federal government’s Home Guarantee Scheme, this allows eligible buyers to purchase a home with a 5% deposit without paying Lender’s Mortgage Insurance (LMI). The property value must fall within regional price caps based on valuation.
How Valuation Differs from Market Appraisal
Many first-time buyers confuse real estate agent appraisals with property valuations. Here’s the key distinction: an agent’s appraisal is often aimed at setting a listing price and is usually optimistic. A bank valuation, however, is independent, conservative, and used for lending purposes. The valuer has no incentive to inflate the price.
Agents may say a property is worth $750,000 because of interest and comparable sales. A valuer might say $720,000 based on stricter data and objective standards. As a buyer, you should always trust the valuer’s assessment more than the agent’s pitch.
What Factors Influence a Property Valuation in Australia?
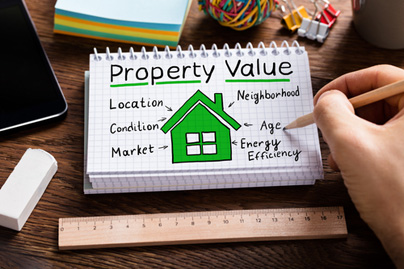
Valuers look at numerous elements to determine a home’s worth. In the Australian context, some of the most important include:
- Comparable sales in the last 6 months within a 2-kilometre radius (for urban homes)
- The property’s location, including school catchments, transport, crime rates, and proximity to CBDs or beaches
- Land size and zoning regulations, especially in NSW, VIC, and QLD where rezoning can boost value
- Building structure and condition, including any unapproved renovations, pest issues, or structural defects
- Recent upgrades or developments, such as new bathrooms, kitchens, solar panels, or pools
The local market also plays a big role. A house in Hobart might get a valuation increase due to rising tourism and population trends, while a similar one in regional WA may be flat due to soft demand.
How the Valuation Process Works in Australia
- You make an offer on a home and apply for a loan.
- The lender orders a valuation—you typically won’t choose the valuer.
- A qualified valuer visits the property, takes measurements, photographs, and inspects the condition.
- The valuer reviews comparable sales, analyses local market trends, and creates a formal valuation report.
- The bank receives the report, which includes a recommended market value and commentary on the property.
The entire process usually takes 2–5 business days depending on location and lender speed.
What Happens If Valuation Comes In Low?
This is a common and stressful scenario for first home buyers. Let’s say you’ve agreed to buy a house for $680,000, but the bank’s valuation comes in at $655,000. The bank will only lend based on the lower figure.
You’ll need to come up with the $25,000 difference or renegotiate with the seller. If you have the funds or a guarantor, you can proceed. If not, the deal may fall through unless the seller adjusts the price.
This is where having a finance clause in your contract is essential. It gives you a way out if your loan is declined due to valuation shortfall.
Can You Dispute a Valuation?
Yes, but it’s difficult. If you strongly believe the valuer made an error, your broker or bank may help you request a second opinion or provide recent comparable sales they missed. However, lenders rarely change valuations unless there’s strong evidence.
It’s also possible to pay for an independent valuation yourself, though lenders may not accept it for loan purposes.
Valuation and First Home Buyer Grants
Each state or territory has different rules for FHOG eligibility, but all have property value caps. Valuation helps determine whether the home falls within those caps. For example:
- NSW: New homes under $750,000 qualify for FHOG ($10,000).
- VIC: Grants available for new homes up to $750,000.
- QLD: FHOG applies to homes valued under $750,000.
- WA, SA, TAS, ACT, NT: Similar caps and conditions, typically tied to value not price alone.
If a property is priced at $745,000 but the valuation exceeds the cap, you may be ineligible for the grant. That’s why valuations are a vital part of grant applications.
Tips for First Home Buyers Dealing with Valuations
Use online tools like CoreLogic or Domain to get a rough estimate before making an offer.
Avoid emotional bidding in auctions—banks don’t care if you overpaid to win.
Request a cooling-off period or finance clause in private treaty sales to protect yourself if the valuation is too low.
Ask your broker to review the valuation report and help you understand any red flags.
Look for properties with clean title, approved structures, and good maintenance—these help valuations come in stronger.
Valuation and Lender’s Mortgage Insurance (LMI)
 Most Australian lenders require LMI if your deposit is less than 20%. The cost of LMI depends on the size of your deposit and the property’s valuation. If the valuation comes in low, your loan-to-value ratio (LVR) increases—making LMI more expensive.
This is where the First Home Guarantee can save you thousands. It lets you buy with as little as 5% deposit and avoid LMI, but only if the home is within value limits. Again, valuation plays a direct role.
For Australian first home buyers, a property valuation is more than a formality—it’s a financial safeguard. It impacts your mortgage approval, determines your deposit needs, and can even affect your access to government grants. In a property market where prices rise and fall quickly, and competition is fierce, valuations keep buyers grounded in data and reality.
Understanding this process helps you approach your first home purchase with confidence. Speak to your mortgage broker, ask to see your valuation report, and don’t hesitate to negotiate if the numbers don’t line up. Knowledge is your best tool—and in this case, it could save you tens of thousands.