
Understanding Off‑the‑Plan Purchases
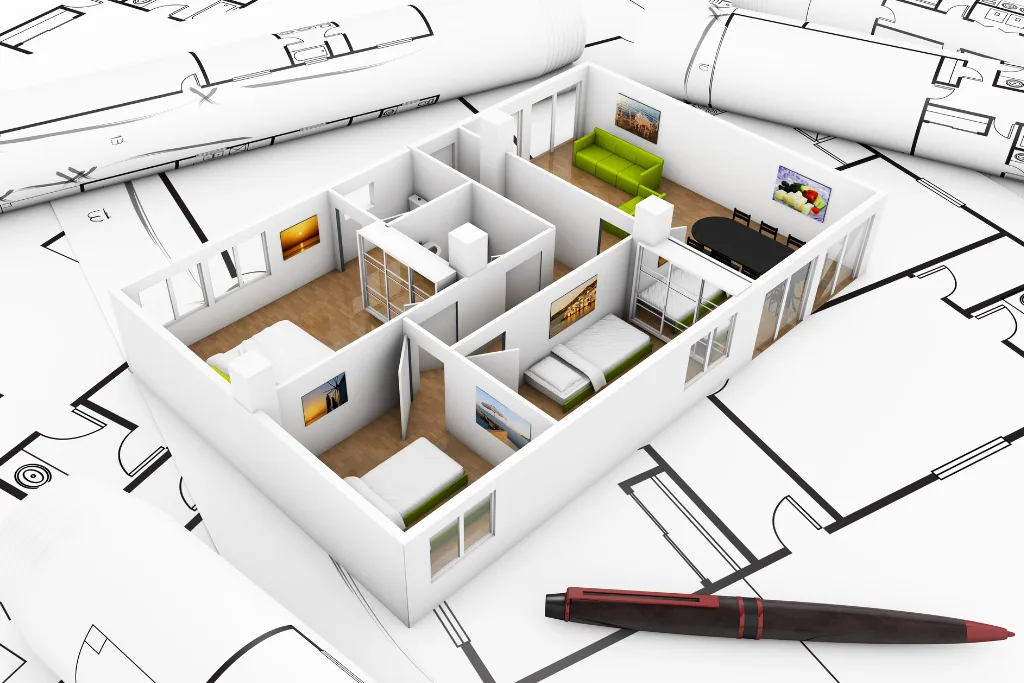
When you buy off‑the‑plan, you agree to buy a property before it’s built or before the title is registered. Often all you have is an artist’s rendering, floor plan and display apartment to make your decision. Usually you pay a deposit—often 5–10%—and the balance is due upon settlement, which could be one or two years later.
This is a popular option for first home buyers in Australia since most government grants and stamp‑duty concessions apply only to new builds, off‑the‑plan apartments or house‑and‑land packages—and not to established homes.
Government Grants and Concessions That Make It Attractive
Across Australia, first home buyers are eligible for a variety of financial incentives that often favour new or off‑the‑plan properties.
The First Home Owner Grant (FHOG) is a lump‑sum payment—typically $10,000, but up to $15,000 in some states—that applies only when buying or building a new home, including off‑the‑plan purchases.
Many states also offer stamp duty exemptions or reductions on off‑the‑plan purchases under certain price caps. For example, in NSW homes under $800,000 may qualify for full exemption; Victorian first home buyers pay no stamp duty on new homes up to $600,000; similar thresholds exist in WA, QLD, SA and TAS.
Beyond state schemes, the First Home Guarantee (previously Loan Deposit Scheme) allows eligible buyers to purchase with as little as 5% deposit—and avoid lender’s mortgage insurance (LMI)—by getting a government guarantee for up to 15% of the loan. Single parents may qualify for a 2% deposit under the Family Home Guarantee.
These combined supports can reduce upfront cash requirements, helping first home buyers enter the market earlier with far less capital than would otherwise be required.
What First Home Buyers Gain from Off‑the‑Plan Properties
Lower Deposit and Cash Flow Benefits
You typically pay only a small deposit (often capped at 10%) up front because developers usually do not demand more than that for off‑the‑plan agreements. This gives you time—often one to two years—to save further or manage your finances before settlement.
Some developers even accept a bank guarantee instead of a cash deposit, allowing you to retain your deposit funds in savings until settlement, earning interest in the meantime.
Stamp Duty and Grant Access
Since FHOG and stamp duty concessions apply predominantly to new builds and off‑the‑plan purchases, first home buyers often save thousands compared to buying established homes. In Queensland, for instance, the total combined benefits—from a $30,000 FHOG plus stamp duty exemption and LMI savings—can exceed $55,000 on properties below threshold values.
Potential Early Capital Growth
If property prices rise while your property is under construction, you will effectively have locked in the earlier price. That means there’s the potential for capital growth to accrue before settlement occurs. Buying early in the release of a development may get you more attractive pricing and first pick of available units.
Personalisation Options
Some projects allow buyers to customise finishes or upgrade fixtures at contract stage—like floorboards, tiles, or appliances—so you can tailor your home to your preferences before it’s built.
Key Risks and Caveats for First Home Buyers
Paying a Premium Above Market Value
Developers typically price off‑the‑plan units based on projected values at completion. If the market stagnates or falls, you may be paying above what similar properties sell for upon completion. That premium may take several years to “catch up” if prices do rise.
Construction Delays and Uncertainty
Settlements may be delayed due to construction delays, delays in subdivision registration, issues obtaining occupancy permits or developer problems. These may force you to continue renting or pay bridging costs longer than anticipated.
Developer Insolvency or Poor Build Quality
If the developer goes bust before completion, or if construction quality is sub‑par, there may be limited recourse. You haven’t seen the finished building, and buyer power in strata structures may be weak. Researching the developer’s track record and engaging a specialised property lawyer is essential.
Sunset Clauses, Contract Risk and Small Print
Contracts usually include sunset clauses allowing either side to cancel if completion is delayed beyond a certain date. Understanding deadlines, penalty clauses, exit rights and deposit terms is crucial. A specialist lawyer can help entrants to understand all liability and obligations upfront.
Oversupply and Local Market Dynamics
If an area becomes saturated with similar apartments, competition may push values down or reduce rental demand. Location matters immensely. New high‑density supply in certain suburbs can undermine longer‑term price growth potential.
Are Off‑the‑Plan Properties Right for First Home Buyers?
Ideal For Those Who Can Tolerate Delay and Uncertainty
If you’re comfortable locking in a small deposit today, taking advantage of government incentives, and you understand delays and market uncertainty, an off‑the‑plan purchase can be a powerful way in. You get time to finance, potential growth, and lower upfront costs.
But Not for Buyers Needing Certainty or Immediate Move‑in
If you need to move in quickly, are risk‑averse or unfamiliar with complex contracts, an established home offers far more certainty. You know exactly what you’re buying, the quality, the neighbourhood and settlement timing.
Financial Position and Grant Caps Matter
Your ability to access First Home Guarantee schemes depends on meeting income caps (e.g. ≤ A$125,000 individual or A$200,000 couple) and property price caps that vary by location. If your target suburb exceeds those limits, the financial incentives may not apply, reducing the appeal of off‑the‑plan buys.
Developer Due Diligence Is Core
You must fully vet the developer’s history, previous projects, reviews, timeliness and any complaints. Where possible, visit completed developments to assess build quality. Always engage a lawyer specialising in off‑the‑plan property before signing any contract.
How to Make Off‑the‑Plan Work for First Home Buyers
Familiarise yourself with the First Home Owner Grant and shared equity schemes in your state:
- In NSW you may receive up to $10,000 FHOG plus a full stamp duty exemption for new homes under $800 k.
- In Victoria FHOG is $10,000 on new homes under $750 k with full stamp duty exemption on properties up to $600 k.
- Similar arrangements exist in QLD (up to $30,000 FHOG and stamp duty waiver), WA, SA, TAS and NT, each with different thresholds and structures.
Confirm eligibility for the First Home Guarantee or Family Home Guarantee, including income limits and property caps. If eligible, these schemes allow you to reduce deposit requirements and avoid LMI but are limited in places and numbers.
Before signing:
- Have a qualified off‑the‑plan property conveyancer or solicitor review the contract.
- Understand the sunset clause—the deadline for the deal to go unconditional or fall over—and your rights if the project is delayed.
- Confirm how the strata plan will work, what happens if defects appear, and whether you can inspect any completed stages before settlement.
Deeply research the developer, visit earlier projects they completed, and even speak to residents if feasible to verify build quality and timeliness.
Smart Entry, with Caution
For many first home buyers in Australia, off‑the‑plan can be a very effective path into home ownership. Government grants and duty relief can substantially reduce upfront costs, smaller deposits and deferred settlement timelines give breathing room, and capital growth in a rising market can reward early buyers.
However, the risks are real: premium pricing, construction delays, developer failings, and market oversupply can all erode the financial upside. You need patience, legal protections, and a clear exit strategy if something goes wrong.
If you understand the risks and carefully vet the developer and context, buying off‑the‑plan can unlock entry to home ownership sooner—and with government support—than almost any other option in today’s market. But if stability, immediate occupancy and certainty matter more to you, an existing home may be a safer first step.